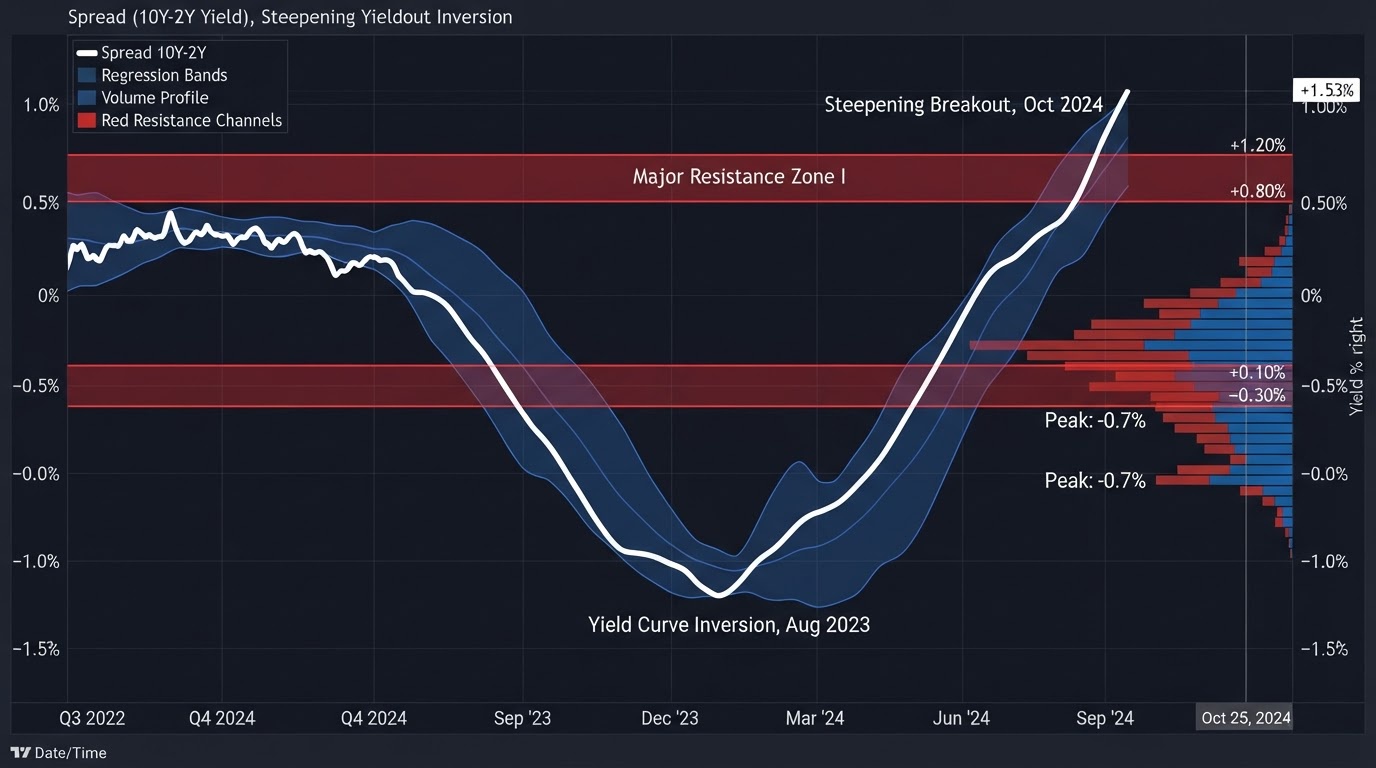
Macrocurrent decodes structural shifts across rates, fiscal cliffs, and foreign exchange imbalances. We deliver institutional-grade predictive analytics, systematic risk indexes, and unhedged high-conviction dossiers before consensus re-calibrates.
Rigorous macro-econometric analysis, cross-border capital flows, and debt sustainability models designed for chief investment officers and allocation committees.
As $9.2T in G7 sovereign debt matures over the next 18 months, our dynamic debt-sustainability engine uncovers the imminent steepening impulse in developed market yields. We model the breaking threshold for central bank balance-sheet absorption, quantitative tightening constraints, and the re-emergence of term premia.
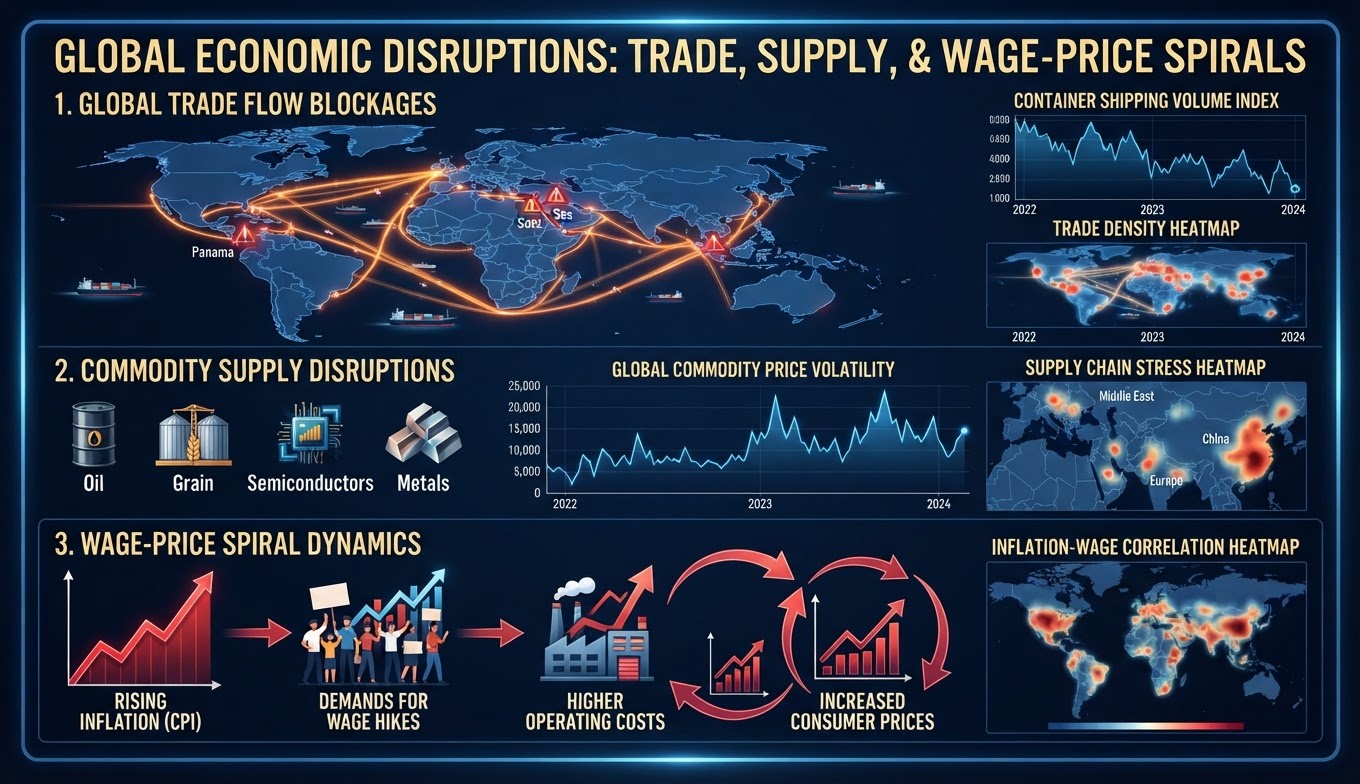
An empirical exploration of the supply-side rigidities in critical energy grids, critical minerals, and de-globalized shipping corridors that prevent central bank terminal policy from dampening persistent median inflation prints.
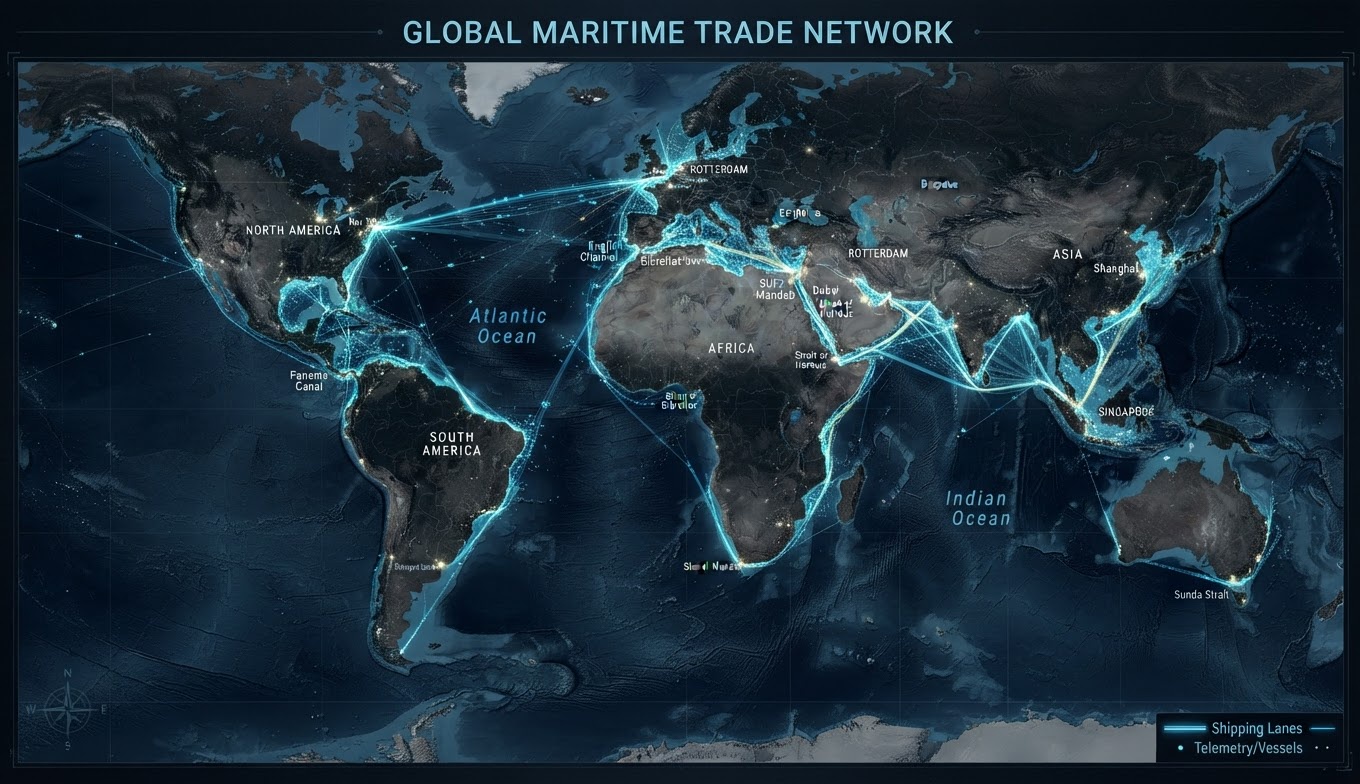
Evaluating the economic friction of routing around maritime conflict zones and friend-shoring semiconductor manufacturing. Detailed calculations of the lasting 120-180 bps input-cost penalty embedded across Western corporate margins.
Our research division avoids generic consensus commentary. Instead, we dissect cross-market contagion channels through four interconnected quantitative coverage pillars.
Predictive parsing of FOMC, ECB, BoJ, and PBoC decision paths using proprietary natural language processing on minutes, shadow-rate forecasting, and bank reserve liquidity metrics.
Geostrategic threat indexing, cross-border capital embargo tracking, bilateral currency settlement architecture, and maritime bottleneck tracking across sensitive maritime choke corridors.
Granular quantification of primary deficits, auction tail-risk metrics, treasury general account (TGA) replenishment ripples, and emerging sovereign credit default contagion probabilities.
Physical supply constraint quantification, Capex depletion metrics across crude, LNG, base metals, and battery chemistry feedstocks driving generational terms-of-trade transfers.
Simulate instantaneous stress testing across asset classes, systemic correlation breakdown, and model portfolio rebalancing vectors under key structural macroeconomic outcomes.
Implied dynamic co-movement coefficients under selected macroeconomic stress condition
| ASSET | SPX | UST 10Y | DXY | BRENT | GOLD | HY SPREAD |
|---|---|---|---|---|---|---|
| SPX 500 | 1.00 | -0.58 | -0.42 | +0.38 | +0.04 | -0.81 |
| UST 10Y | -0.58 | 1.00 | +0.32 | -0.45 | +0.62 | +0.51 |
| DXY (USD) | -0.42 | +0.32 | 1.00 | -0.64 | -0.39 | +0.36 |
| Brent Oil | +0.38 | -0.45 | -0.64 | 1.00 | +0.29 | -0.31 |
Mean-variance optimization with tail-risk penalty constraints
Real-time trade floor perspectives, granular chart dissections, and audio briefings directly from our Chief Economists across New York, London, and Singapore desks.
Dr. Marcus Vance and FX Strategist Lin Wei explore repo collateral scarcity, Japanese life insurer FX hedge roll-overs, and swap basis widening.
Historical regressions illustrate that the steepening of the 2s10s curve from -50 bps towards positive territory precipitates maximum credit spread expansion.
Consensus forecasts for electrification assume a smooth copper extraction trajectory. However, ongoing smelting capacity reductions and Latin American water restrictions mean current LME warehouse inventories are severely underpricing tail-risk.
Bespoke integration options engineered for institutional scale. Empower your investment committee with unvarnished empirical modeling, low-latency data feeds, and direct counsel.
Tailored forecasting models mapped to your fund's unique portfolio mandate. Scenario stress testing for idiosyncratic sovereign exposures and foreign exchange liabilities.
REST & WebSocket programmatic feeds streaming our quantitative risk indices, term-structure analytics, and central bank sentiment scores directly into your order and risk management systems.
Exclusive invitation-only closed convenings conducted under Chatham House Rule. Engage directly with former central bank governors, treasury officials, and macro hedge fund founders.
On-call direct strategic consultation with Macrocurrent's Chief Strategists. Support for board-level strategic asset allocation reviews and tactical hedging interventions.